Apple (NASDAQ: AAPL) may be the world’s largest company, with a $3.4 trillion market cap, but that doesn’t mean it will retain that place forever. Some cracks in Apple’s armor could make it vulnerable, allowing other companies to pass Apple in market cap.
Here are three stocks that could be worth more than Apple five years from now.
What’s wrong with Apple?
Apple isn’t the company it used to be. It used to be at the forefront of innovation and consistently released game-changing products. It hasn’t done that for some time, and even the latest iPhone (iPhone 16) seems to be struggling despite its much-hyped Apple Intelligence features.
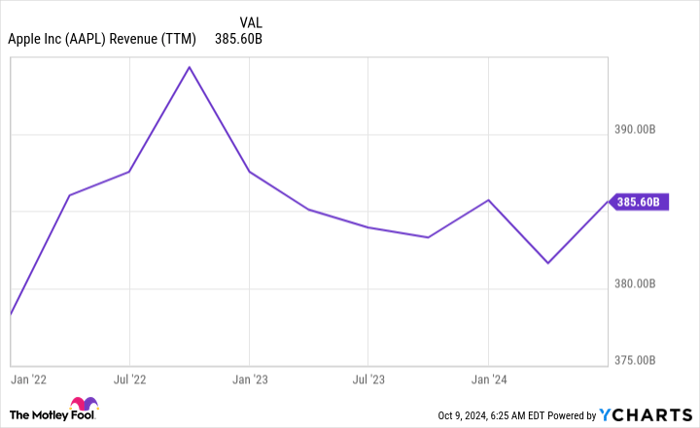
All of this adds up to a business that hasn’t grown its sales since 2022.
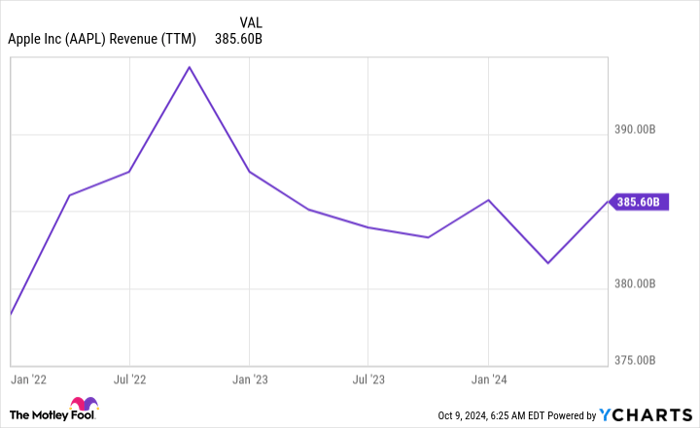
AAPL Revenue (TTM) data by YCharts
Despite that, Apple’s stock fetches a premium valuation, trading for 30.5 times forward earnings.
That’s a premium price tag for a company that hasn’t grown at all, leaving it susceptible to other stocks surpassing it. If it doesn’t show growth soon, the premium will not be maintained.
Plenty of other stocks could surpass Apple if this happens, and all of them are likely better investments right now.
Nvidia and Alphabet are within striking distance
Five years from now, the three companies that I think can pass Apple are Nvidia (NASDAQ: NVDA), Microsoft (NASDAQ: MSFT), and Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL). These three are obvious choices, as they round out the rest of the top four largest companies in the world.
Understanding why these three could surpass Apple is key, as they all have different reasons.
Starting with the second-largest company, Nvidia, it is nipping at Apple’s heels. It’s only 5% away from dethroning Apple, and with the massive demand for its graphics processing units (GPUs) used for artificial intelligence (AI) model creation, it’s nearly a surefire bet to be larger than Apple.
Despite its incredible growth this year, Wall Street still expects 42% revenue growth for fiscal year 2026 (ending January 2026). That far exceeds anything Apple will put up, but Nvidia trades for 47 times forward earnings — a far greater price tag than investors are paying for Apple.
It will take some time for this premium to come down, but I think it’s possible over the course of five years.
Microsoft is next in line, only 11% away from the top spot. Microsoft has been a stalwart, growing revenue by more than 15% over the past year. It also rides on the back of AI, with its cloud computing division, Azure, leading the way for the company. It trades for 31.5 times forward earnings, nearly identical to Apple’s price tag.
However, Microsoft actually has the growth to support this valuation. So, as the market comes to its senses with Apple stock, don’t be surprised to see Microsoft pass Apple in market cap.
While Nvidia and Microsoft could easily surpass Apple in the next few years, Alphabet’s chances are slightly lower.
Alphabet needs help from a valuation standpoint to pass Apple
Alphabet’s case rests on its premium increase and Apple’s decrease. Alphabet’s revenue growth has been in the low teens for the past year, which places it far above Apple.
However, Alphabet doesn’t fetch the premium Apple does and trades for 21.5 times forward earnings. That’s cheaper than the S&P 500, which trades at 23.5 times forward earnings.
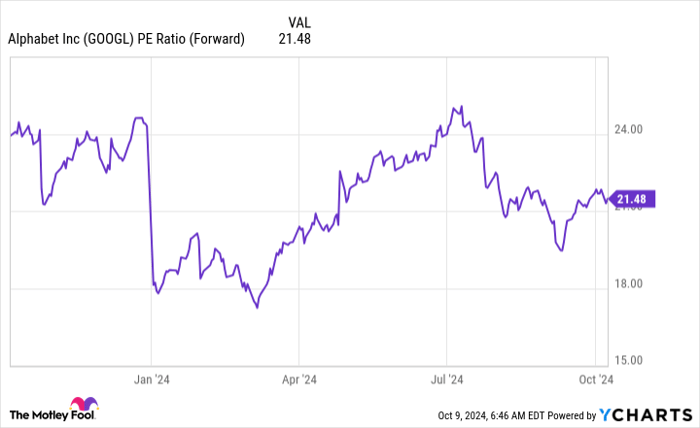
GOOGL PE Ratio (Forward) data by YCharts
If Alphabet were to fetch the same premium as Apple (30.5 times forward earnings), it would have 42% upside. That would give it a $2.88 trillion market cap, only 19% away from Apple. If Alphabet continues its pattern of growth and Apple continues its pattern of stagnation, that would be an easy gap to close over five years, allowing Alphabet to surpass Apple.
Additionally, Apple’s premium could decrease to the market average, which would provide a similar effect to Alphabet’s rise.
I think there is a strong chance Apple is worth less than these three if it doesn’t start growing sales soon. If it launches a new product that’s a hit, then these projections likely won’t hold true.
Don’t miss this second chance at a potentially lucrative opportunity
Ever feel like you missed the boat in buying the most successful stocks? Then you’ll want to hear this.
On rare occasions, our expert team of analysts issues a “Double Down” stock recommendation for companies that they think are about to pop. If you’re worried you’ve already missed your chance to invest, now is the best time to buy before it’s too late. And the numbers speak for themselves:
- Amazon: if you invested $1,000 when we doubled down in 2010, you’d have $21,022!*
- Apple: if you invested $1,000 when we doubled down in 2008, you’d have $43,329!*
- Netflix: if you invested $1,000 when we doubled down in 2004, you’d have $393,839!*
Right now, we’re issuing “Double Down” alerts for three incredible companies, and there may not be another chance like this anytime soon.
*Stock Advisor returns as of October 7, 2024
Suzanne Frey, an executive at Alphabet, is a member of The Motley Fool’s board of directors. Keithen Drury has positions in Alphabet. The Motley Fool has positions in and recommends Alphabet, Apple, Microsoft, and Nvidia. The Motley Fool recommends the following options: long January 2026 $395 calls on Microsoft and short January 2026 $405 calls on Microsoft. The Motley Fool has a disclosure policy.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.