Key Points
-
Google Search continues to grow despite the growing use of AI chatbot tools like Gemini and ChatGPT.
-
Google Cloud’s backlog grew to $514 billion at the end of the second quarter.
-
Alphabet’s stock is the cheapest of the “Magnificent Seven” stocks when comparing price to projected earnings.
- 10 stocks we like better than Alphabet ›
With over half of September gone, it’s never too early to begin thinking about what investments are worth buying heading into the fourth quarter (Q4) of 2026. Plenty of stocks have momentum behind them, but one in particular that I believe is being overlooked is Alphabet (NASDAQ: GOOG)(NASDAQ: GOOGL).
Through market close on Sept. 15, Alphabet is up 10.5% this year. And while double-digit percentage gains are always welcomed, it’s underperforming the S&P 500. This underwhelming performance — and the current prices it’s trading at — is also why Alphabet looks like a good buy right now. I expect the stock to finish the year strong and continue being a great long-term investment.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
There’s Google Search and then everyone else
Alphabet is fairly diversified, but its bread and butter has always been (and will remain for the foreseeable future) Google Search. In Q2, Google Search accounted for nearly 53% of Alphabet’s $119.8 billion in revenue.
There were initial concerns that artificial intelligence (AI) chatbots, such as ChatGPT or Alphabet’s own model, Gemini, would hurt Google Search because people would prefer conversational AI answers over traditional search results. However, Google Search’s business is as strong as ever. It has done a good job using traditional search, AI Overviews, and AI Mode to create an integrated Search experience rather than letting AI take away eyeballs.
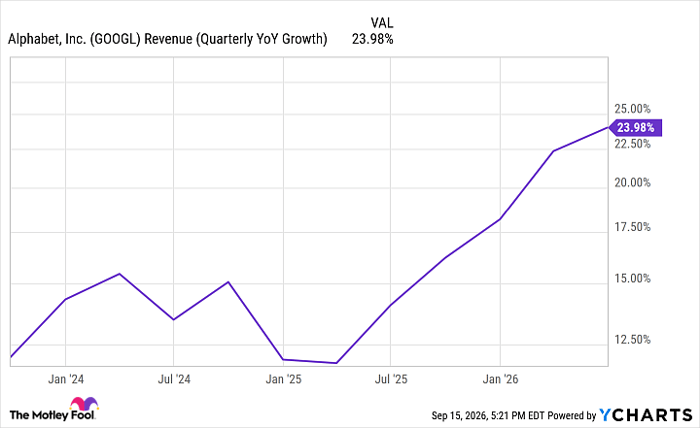
Google has always held a monopoly on search, and that’s still the case, with a 91%global marketshare. Very few companies in any industry command a position as dominant as Google does in search. With its high-margin advertising business flourishing because of it, I expect Alphabet’s revenue to continue growing into the 20% range over the next few quarters.

GOOGL Revenue (Quarterly YoY Growth) data by YCharts.
Google Cloud’s growth isn’t slowing down
Like other AI hyperscalers (companies that own the major data centers), Alphabet’s main growth engine right now is its cloud platform, Google Cloud. It trails Amazon Web Services (AWS) and Microsoft’s Azure in market share — 28%, 21%, and 14%, respectively — but it’s growing the fastest out of the big three.
In Q2, Google Cloud revenue jumped 82% year over year to $24.8 billion, with much of the growth due to growing enterprise customer adoption. Plenty of growth appears ahead, with Google Cloud’s backlog rising $50 billion from Q1 to $514 billion.
Right now, Alphabet has a capacity issue, not a demand issue. That’s why it’s investing so much in new data centers and other AI infrastructure, so it can take on more customers and convert that backlog into real revenue. It expects to recognize at least half of its backlog over the next 24 months.
If that happens, Google Cloud will remain the key driver of Alphabet’s continued growth.
Image source: The Motley Fool.
Alphabet’s value seems very good right now
At the time of writing, Alphabet was trading at 16.7 times its projected earnings over the next 12 months. That’s the lowest among the “Magnificent Seven” stocks and much lower than its historical trading range. That in itself doesn’t make Alphabet a great buy right now, but when you look at its business trajectory, it’s almost too good to pass up.

GOOGL PE Ratio (Forward) data by YCharts.
You have a company with a monopoly in its core business, a fast-growing cloud business, a powerhouse in YouTube, and a dividend that is one of the most overlooked parts of Alphabet’s stock. Granted, its dividend yield is minimal at 0.25%, but it’s a dividend nonetheless. And you can almost guarantee it will keep increasing over the years. Since it began paying one in June 2024, it has had two consecutive 5% increases, including one this April.
Of course, Alphabet’s dividend is far from the stock’s selling point, but it’s a nice-to-have perk that will keep paying off over time. I’d invest in Alphabet for the long haul without thinking twice.
Should you buy stock in Alphabet right now?
Before you buy stock in Alphabet, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Alphabet wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $412,074!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,314,319!*
Now, it’s worth noting Stock Advisor’s total average return is 932% — a market-crushing outperformance compared to 209% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
*Stock Advisor returns as of September 17, 2026.
Stefon Walters has positions in Apple and Microsoft. The Motley Fool has positions in and recommends Alphabet, Amazon, Apple, Meta Platforms, Microsoft, Nvidia, and Tesla. The Motley Fool has a disclosure policy.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.