The whipping post

Analysis of Qualcomm’s Value and Potential Growth Uncovering the Untapped Value in Qualcomm Stock

Qualcomm, the seasoned mobile-chip powerhouse listed on NASDAQ under QCOM, has surprisingly emerged as a suitor’s dream in the volatile vortex of 2024. Weathering the tumult of a post-pandemic gadget spree, Qualcomm’s shares have surged to unprecedented altitudes, boasting a stalwart 40% climb since the year’s advent.

The rationale underpinning this meteoric rise is anchored in Qualcomm’s clever cultivation of novel consumer vistas, ushering in winds of fortune that swirl with promise. While the smartphone sector might languish, Qualcomm’s forays into burgeoning markets spell an uptick in profitability, rendering the stock a veritable treasure trove of potential.

The Acceleration of the Automotive Sector and the Revving of PC Sales

Resurrecting from the ashes of uncertainty, Qualcomm now revels in the revitalization of the smartphone domain thanks to the buoyant demand for its premium 5G connectivity chips. Spearheading Qualcomm’s revenue upswing, these high-end chips fetch higher prices, outshining the market’s lackluster performance.

But the plot thickens. Qualcomm’s long-slumbering PC venture promises a renaissance with the impending launch of its Snapdragon X Elite laptop chips. Crafted for Microsoft Windows laptops on the storied Arm Holdings architecture, akin to Apple’s lauded MacBook lineup, this venture unearths a fresh territory ripe for Qualcomm’s conquest. A domain traditionally lorded over by Intel and AMD, Qualcomm’s potential market incursion drips with promise, offering a lucrative pedestal for growth akin to its erstwhile automotive exploits.
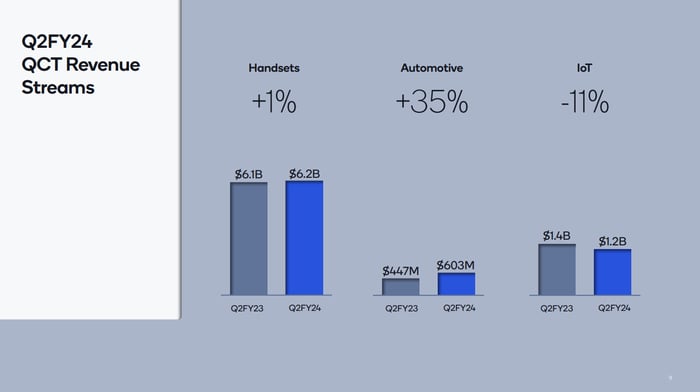
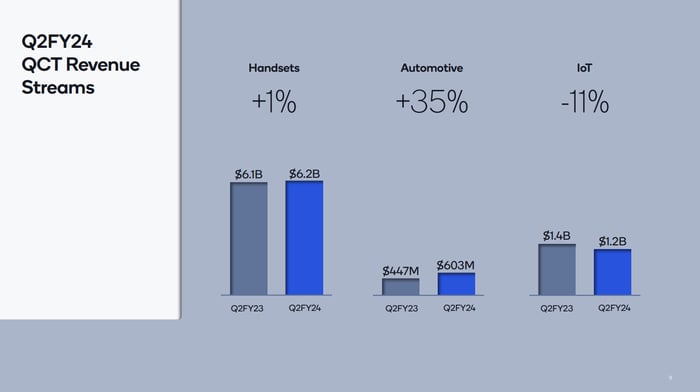
A chart showing Qualcomm's smartphone revenue stabilizing at 1% in the last quarter, but automotive growing 35% and IoT down 11%.

Qualcomm’s revenue is starting to look very different from historical norms. Source: Qualcomm.

The Coveted Corner of Margins

Amidst the cyclical undulations of the smartphone realm, Qualcomm boasts a resilient business model that perennially delivers robust profitability. As the consumer expenditure landscape convalesces from the pandemic-induced convulsions and rate hikes, Qualcomm’s profit margins are poised to thrive.

See also  <!DOCTYPE html><html><head><title>The Time is Ripe for Small Caps</title></head><body><h2>Resilient Consumers Powering Small Caps Higher</h2><p><em>Traditional wisdom in financial markets suggests never underestimating the fortitude of the American spender.</em></p><p>According to renowned investor Louis Navellier, this adage rings true, especially in the recent climate. The latest retail sales data reinforced this notion, with US retail sales surging beyond forecasts in September. The Commerce Department reported that retail purchases saw a 0.4% increase, bolstered by a 0.7% climb in sales excluding autos and gasoline stations. This ongoing trend reflects robust consumer spending, a primary driver of economic growth and demand.</p><h3>All Eyes on Consumer Health</h3><p>Consumer spending is a linchpin of the US economy, commanding nearly 70% of the GDP. Despite mixed indicators on consumers' financial health, their purchasing power remains robust, propelling economic expansion. With inflation on a downward trajectory and anticipated interest rate cuts, the stage is set for a bullish stock market environment.</p><h3>The Rise of Small Caps</h3><p>As interest rates decline, small-cap stocks emerge as prime beneficiaries. These entities are well-positioned to capitalize on lower rates due to their typically higher debt burdens compared to larger corporations. The market's recent disparity, favoring larger-cap stocks, creates an opportune moment for small caps to shine.</p><div><img src="https://investorplace.com/wp-content/uploads/2024/10/sp-vs-iwm-10.22.24.png" alt="Chart comparing the performance of large-cap and small-cap stocks" width="969" height="588"><p>Source: StockCharts.com</p></div><p>Recent market dynamics have shown signs of small caps rallying, outperforming their larger counterparts. For instance, during the initial weeks of October, the Russell 2000 index surged by 2.7%, overshadowing the S&P 500 and Dow Jones Industrial Average. This incremental growth hints at a potential shift towards small-cap dominance in the coming months.</p><div><img src="https://investorplace.com/wp-content/uploads/2024/10/iwm-catching-up-in-returns-10.22.24.png" alt="Chart highlighting the outperformance of the Russell 2000 index" width="969" height="588"><p>Source: StockCharts.com</p></div><p>Additional factors, such as seasonality, the upcoming presidential election, and robust Q3 earnings, further bolster the case for small-cap stocks. These tailwinds, coupled with positive market sentiment, fuel optimism among investors like Louis Navellier.</p><h3>Bullish Sentiments Across Analysts</h3><p>Joining the chorus of optimism is Jason Bodner, the mind behind the quantitative investment service, Quantum Edge Pro. With a data-driven approach similar to Navellier's, Bodner analyzes market movements using sophisticated algorithms to unearth opportunities driven by institutional investors.</p><p>Both Navellier and Bodner exemplify a trend in modern market analysis, blending human expertise with technological prowess to navigate the complexities of today's financial landscape. Their shared optimism in small-cap stocks reflects a broader consensus that the time is indeed ripe for these agile market players.</p></body></html><html><head></head><body>Insights into the Surge of Big Money Investors in Small Cap Stocks

Moreover, Qualcomm’s profit reservoirs face sustenance from the burgeoning PC and automotive chip sectors. As these ventures yield bountiful returns, Qualcomm’s margin coffers are destined for augmentation, setting the stage for brighter days.
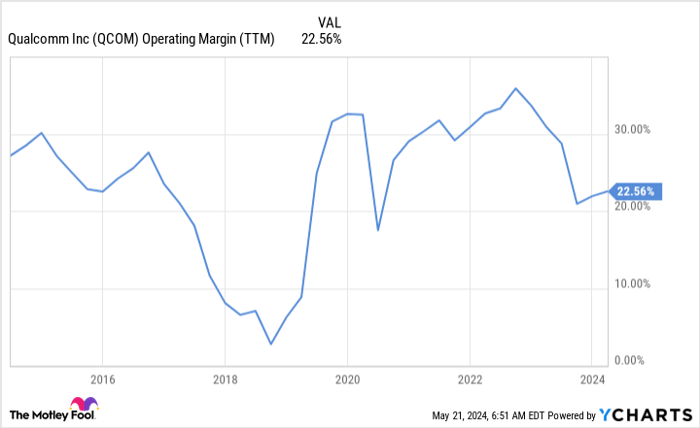
QCOM Operating Margin (TTM) Chart

Data by YCharts. TTM = trailing 12 months.

While Qualcomm may not scale the semiconductor Olympus at breakneck speeds, the confluence of elevated ASPs in smartphone chips and nascent growth channels like Windows laptops and automotive chips hints at a modest low-teens upswing in earnings per share (EPS) over the ensuing years.

A bargain at 27 times trailing-12-month EPS or 18 times free cash flow, Qualcomm morphs into an irresistible proposition of enduring worth.

Is Qualcomm Worth a $1,000 Gamble?

Prior to plunging into Qualcomm’s stock realm, pause to ponder:

The celebrated minds at Motley Fool Stock Advisor have pinpointed 10 red-hot stocks, visions of meteoric returns shimmering in their gaze… with Qualcomm conspicuously absent from the roster. A tantalizing prospect looms, promising eye-popping returns in the forthcoming era.

Reflect on the historic moment when Nvidia graced this list in 2005 – a $1,000 dalliance then would have swelled to a staggering $635,982 now!*.

Stock Advisor bequeaths a roadmap to prosperity, guiding investors through the labyrinth of portfolio construction, interspersed with analyst insights and bi-monthly stock revelations. Since 2002, Stock Advisor has eclipsed the S&P 500’s return, transcending mere investment sagas to apocryphal tales of boundless returns*

Witness the 10 stocks »

*Stock Advisor returns as of May 13, 2024


5 Stocks Our Experts Predict Could Double In the Next Year

By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.